In this article
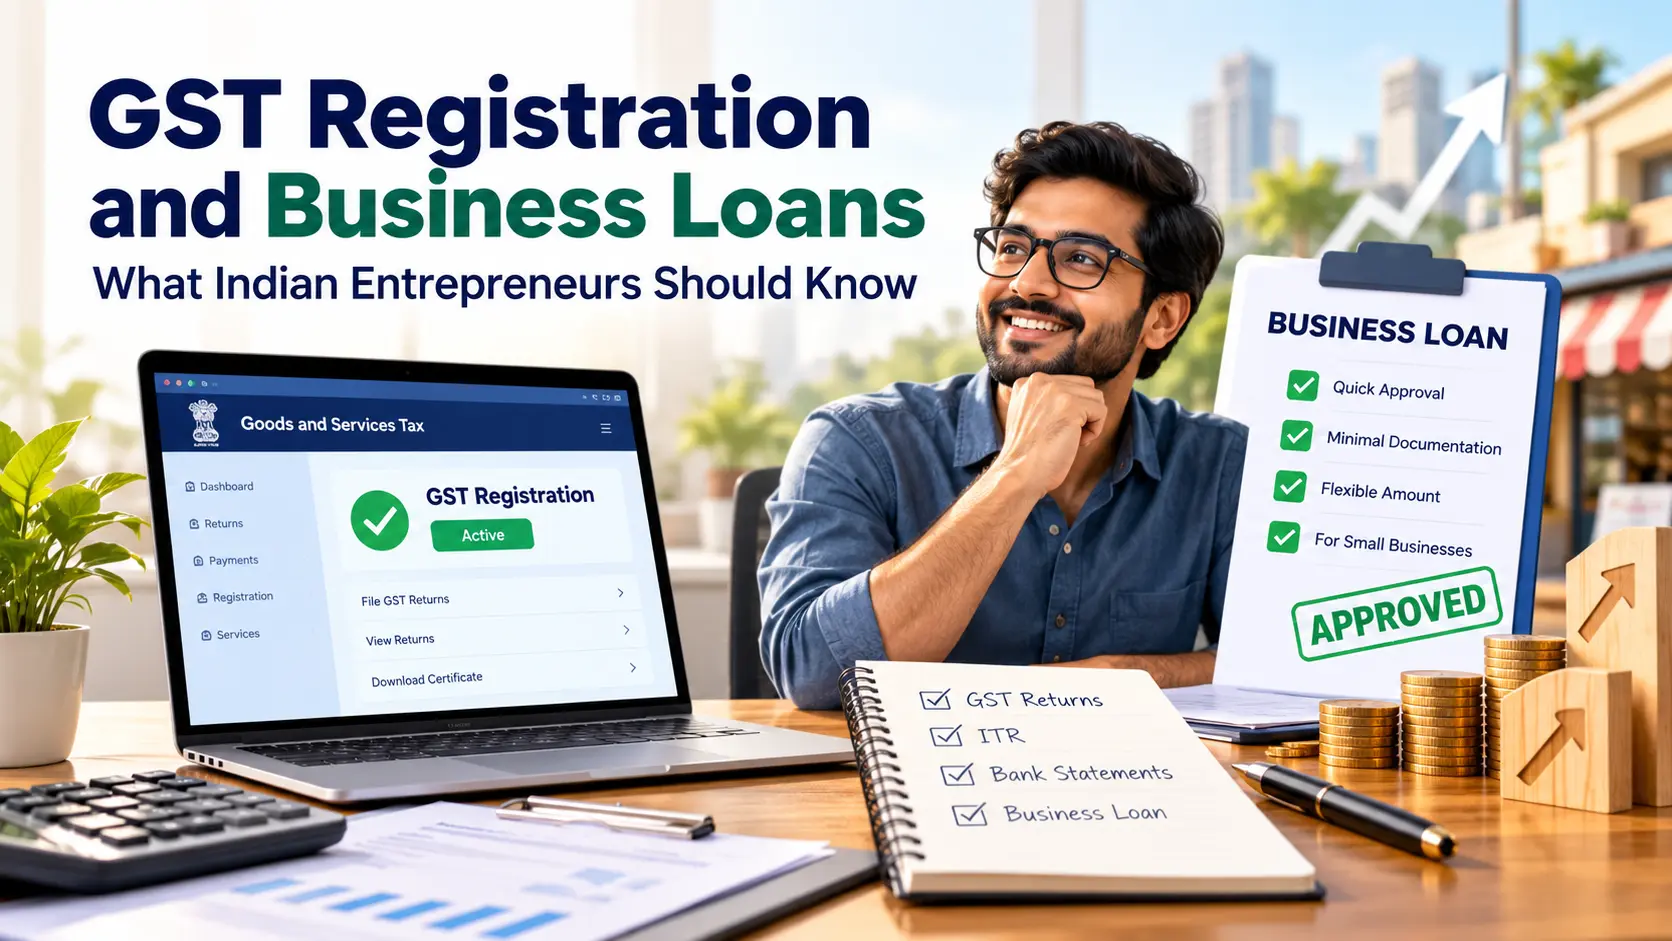
Ask any small business owner in India what keeps them up at night, and money usually tops the list. Stock has to be bought, salaries can’t wait, and that supplier wants payment upfront. This is where a gst business loan starts making sense. Your GST registration isn’t just a compliance chore. It can actually open doors to funding. Here’s how the two connect, what lenders look at, and what you should keep ready.
What Is a GST Business Loan and How Does It Work?
It isn’t a special product with a fancy label. It’s a regular business loan where the lender leans on your GST registration and filed returns to judge how your business is doing. Since GST returns show your monthly sales, lenders get a verifiable picture of your turnover without digging through piles of paper. That means quicker checks and fewer doubts.
Why Does GST Registration Matter for Getting a Business Loan?
Registration is mandatory once your turnover crosses ₹40 lakh for goods or ₹20 lakh for services. Limits are lower in some special category states. But beyond the legal side, it works as proof that your business is real and running.
For a gst business loan, that proof carries real weight. Regular returns tell a lender you’re organised and your income is steady. Skipped filings? They say the opposite, and lenders notice.
What Are the Business Loan Eligibility Rules for a GST Business Loan?
Every lender has its own checklist, but business loan eligibility generally comes down to these:
- Business vintage: most lenders want at least 6 months to 2 years of operation
- Turnover: a minimum annual figure, which differs from lender to lender
- Credit score: 700 or above usually helps a lot
- GST registration: valid, with returns filed on time
- Applicant age: typically between 21 and 65
- Business type: proprietorship, partnership, or company, all can apply
The wider business loan requirements also include clean bank statements and a stable repayment record. Traditional banks can be strict about all this. Newer digital lenders tend to be more flexible, especially for smaller loan amounts.
Is ITR Required for a GST Business Loan?
Mostly, yes. Think of it this way: GST shows what you sold, while your income tax return shows what you actually earned after expenses. Lenders like seeing both.
For itr for business loan applications, the last two years of returns are what’s commonly asked for. Haven’t completed two years yet? Don’t panic. Some lenders will accept six to twelve months of bank statements along with your GST filings. It’s worth asking before you assume you’re out.
What Documents Are Required for a Business Loan?
Nobody enjoys running around for paperwork. So here’s the usual list of documents needed for business loan applications, which also applies when you’re going for a gst business loan:
- Identity and address proof: Aadhaar, PAN, passport, or voter ID
- Business proof: GST certificate, Udyam registration, or shop establishment licence
- Financial records: 6 to 12 months of bank statements
- Tax documents: ITR for the last 1 to 2 years and GST returns
- Photographs and a signed application form
Banks often want a thick file, original copies, and a few branch visits on top. That’s where it gets tiring, especially when you’re already juggling a shop, staff, and customers.
This is where mPokket makes life easier. It’s a fully digital platform, so you apply from your phone. No queues, no branch trips. KYC is quick, the paperwork stays minimal, and you can upload documents right in the app. Loan offers come through its RBI-regulated lending partners, so you’re not dealing with shady middlemen. Small-ticket needs, like restocking inventory or covering a payment gap, don’t have to wait weeks for approval. When your cash flow is tight and time matters, that speed and simplicity count for a lot. It’s worth checking the app for the latest loan options and requirements before you apply.
How Can You Improve Your Chances of Getting a GST Business Loan Approved?
A few habits make a bigger difference than people think:
- File GST returns on time, every time. Even one or two late filings can raise eyebrows.
- Keep your bank account active. Route business transactions through it so the statements tell a clear story.
- Check your credit score first. Fix errors or clear small dues before applying.
- Ask for what you need. Overshooting the amount can hurt your approval odds.
- Match your records. If your GST turnover and ITR figures differ wildly, expect questions.
How Can Small Businesses Build a Stronger Financial Foundation?
Getting a business loan is one part of running a business. Staying financially prepared for the next opportunity is just as important. Whether you run a local shop, a service-based business, or a growing online company, keeping your records organised can make everyday financial decisions much easier. It also helps when a lender wants to understand your business before offering credit.
Start with the basics. Keep personal and business transactions separate wherever possible, review your bank statements regularly, and make sure your GST returns reflect your actual business activity. If you are investing in advertising, new equipment, or a digital platform, track what you spend and what you get in return. These small habits can give you a clearer picture of where your money goes and how much you can realistically afford to repay.
Why Digital Readiness Matters for Modern Businesses
Businesses today rely on more than physical stock and a good location. Online visibility, customer trust, and digital security can all influence how a company attracts customers and manages its operations. For instance, understanding what your internet provider’s IP address says about you online can help business owners become more aware of their online identity and privacy.
If your business depends on search traffic, it is also worth understanding how customers discover brands through AI-powered search tools. Exploring the best AI visibility service providers for brands competing in AI search can help you understand the changing ways businesses build an online presence. Similarly, what PPC management looks like now that Google Ads runs more on AI offers useful context for businesses that spend money on paid advertising and want to make their marketing budgets work harder.
These activities may seem unrelated to GST registration at first, but they are part of the bigger picture. A business that understands its costs, measures its marketing results, and maintains reliable records is better placed to decide when borrowing makes sense and when it is better to wait.
Planning Investments Before You Borrow
Before applying for a loan, write down exactly what the money will be used for. Buying inventory ahead of a busy season is different from funding a long-term technology project. The first may generate revenue relatively quickly, while the second could take months to deliver results. Your repayment plan should reflect that difference.
If you are considering AI tools to improve productivity, for example, a review such as Higgsfield AI Review 2026: Features, Pricing, Video Tools and What It Can Actually Do can help you assess a digital tool before committing money to it. Businesses planning larger technology initiatives may also benefit from understanding the 10 skills you need to succeed in AI project management, particularly when projects involve multiple people, ongoing costs, and measurable business goals.
The same thinking applies to physical investments. A company preparing for a trade show should calculate its exhibition costs, expected leads, and potential sales before committing to a stand. This guide to what makes an exhibition stand successful in Hannover provides useful design and planning insights for businesses considering that kind of investment.
The important thing is not to borrow simply because a loan is available. Borrow when the planned expense has a clear purpose, the repayment schedule fits your cash flow, and you have considered what could happen if sales are slower than expected.
Protecting Your Business as It Grows
Financial preparation also means protecting the business from risks that may not show up in a spreadsheet. Digital accounts, customer information, company reputation, and access to essential services can all affect business continuity. Taking sensible precautions early is often easier than dealing with a problem after it occurs.
For online accounts, learning how passkeys work without passwords can introduce you to a more secure way of signing in to supported services. If your business depends heavily on its founder or chief executive, it is also worth considering when a CEO’s personal reputation becomes a business risk. Customer confidence and public perception can have a direct bearing on sales, partnerships, and long-term growth.
Even purchases that seem less connected to finance deserve proper planning. A home entertainment business, for example, may need to understand display requirements, installation costs, and customer expectations before investing in equipment. A practical resource such as the 120-inch projector screen guide for an immersive home theatre experience illustrates why checking specifications and suitability before spending can prevent avoidable costs.
For a small business owner, the lesson is simple: every major expense deserves a little research, a realistic budget, and a clear reason for spending. A business loan can support that process, but it works best when it is part of a broader plan rather than a quick fix for ongoing cash flow problems.
Conclusion
If your business is registered, filing properly, and needs working capital, yes, it’s usually worth a serious look. A gst business loan can help you stock up before the festive rush, buy equipment, or simply smooth out cash flow when payments get delayed.
Just compare interest rates, processing fees, and repayment terms before signing anything. And pick a lender that respects your time as much as your numbers. Keep your returns clean, keep your documents handy, and the funding part gets a lot less stressful.
Use the key points in this guide to understand the topic and make more informed decisions.

This guide is researched and edited using relevant documentation, reliable sources and publicly available information.
Was this guide helpful?
Your feedback helps us improve future guides.